Your situation

Capital gains decisions

How and when you sell often matters as much as what you sell.

A couple walking across the lawn in front of their country house

What are you looking to sell off?

Choose as many as apply.

Search to compare financial advisers.

Get the timing right

Good capital gains tax advice is mostly about sequencing. The gain on a property, a share portfolio or a company is largely fixed; what you can still control is when the disposal happens, whose name it happens in, and what surrounds it: allowances, losses, wrappers and reliefs. Those choices are worth real money, and they close once the sale completes.

An independent adviser works alongside your accountant on exactly these decisions. The accountant computes and reports; the adviser plans the disposal and what happens to the proceeds. Our introduction to a vetted, FCA-regulated adviser is free and without obligation.

Is this you?

  • You are selling a second property or a buy-to-let.
  • You hold a large single shareholding, from an employer scheme or an inheritance, with a big built-in gain.
  • You have a general investment account built up over years that has never been rebalanced because of the tax.
  • You are selling a business (there is a separate page for that: Selling your business).

How an independent adviser helps with a disposal

Timing against tax years

Completing either side of 5 April changes which year the gain lands in, which rates apply, and how many annual exempt amounts you can use. Phasing a large disposal across two tax years is one of the oldest tools in planning, and still one of the most effective.

Using both of a couple’s positions

Transfers between spouses and civil partners are normally free of capital gains tax, which means a disposal can often use two annual exemptions and two sets of tax bands rather than one. It has to be done properly and in advance.

Losses, reliefs and wrappers

Realised losses offset gains, unused losses carry forward once reported, and reliefs from BADR on business sales to private residence relief on property each have conditions worth checking early. Future gains can be sheltered in ISAs and pensions so the same problem shrinks over time.

A plan for the proceeds

The disposal is half the job. An adviser also builds the reinvestment plan: what the money is for, which wrappers it fills, and how it is invested once the tax position is settled.
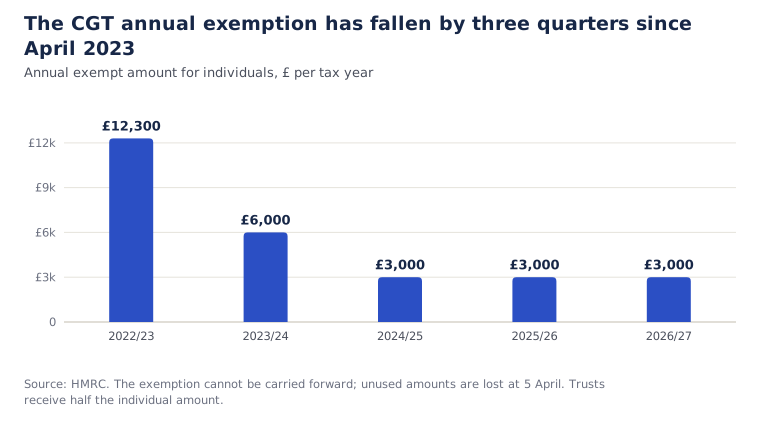
The CGT annual exemption has fallen by three quarters since April 2023
The capital gains annual exemption was £12,300 as recently as 2022/23. It is £3,000 today, and it cannot be carried forward. The smaller the exemption, the more the other tools matter.

Where the savings actually come from

Illustrative only. Figures use 2026/27 rates and assume the spouse has £30,000 of unused basic rate band in each year.

A higher rate taxpayer holds £300,000 of shares from an old employer scheme with a built-in gain of £240,000. Sold in one go, the tax is 24% on £237,000 after the £3,000 exemption: £56,880.

Now the same disposal planned. Half the holding is transferred to a spouse first, which is free of capital gains tax. Each of them sells half of their share in late March and the other half in April, across two tax years. That gives four annual exemptions instead of one, worth £9,000 more, and lets the spouse's unused basic rate band tax £60,000 of gain at 18% rather than 24%.

The tax comes to around £51,120, a saving of roughly £5,760. Not life-changing on its own, which is the honest point: with the exemption at £3,000, the big wins in capital gains planning come from using both spouses' rates, using losses, and then moving the proceeds into ISAs and pensions so the next gain is not taxed at all. £20,000 each into ISAs every April is the quiet part of the plan that adds up.

For a single property, most of that is not available: one disposal is one tax year, whatever the completion date. What is still open is whose name the property is in before exchange, whether losses elsewhere can be used, and where the money goes afterwards.

Key facts for 2026/27

Last reviewed 30 October 2026

What happens when you get in touch

You tell us what you are selling, roughly what it is worth and what you paid for it, and when you would like to complete. One of our team calls you within a working day. We then introduce you to an adviser who works alongside accountants on disposals like yours, usually within a week, and the first meeting is free and without obligation. If what you need is a computation rather than a plan, we will tell you that an accountant is the right call.

Find your adviser
★★★★★“Professional but informal: after a ten minute chat I was set up with a financial adviser. Really easy and friendly.” · Graham
★★★★★“They took time to assess my specific needs and match me up with a financial adviser with appropriate expertise.” · David
★★★★★“A personal, tailored service like this is invaluable and very reassuring.” · Louise
★★★★★“Asked the right questions, no pushing particular products, and put me in touch with an independent FCA adviser in my area.” · Lucie
★★★★★“I was quickly assigned to an IFA who helped me more with my pension than I’ve received elsewhere.” · Natalie
★★★★★“Kya took the worry out of finding the right company to work with, and it was all done within 24 hours.” · Ruth
★★★★★“Communication with IFA Connect was first class at all stages, and the local IFA is of high calibre.” · Firghil
★★★★★“Luke put me in touch with a financial adviser who met my needs. Excellent, quick and friendly service.” · Adrian
★★★★★“A great experience. I got connected with the adviser very quickly, thanks!” · Paulina
★★★★★“Luke responded within the day and proposed an IFA. The introductory call went well and we are exploring further.” · Mr Makin
★★★★★“I was put in touch with a local financial adviser and his help has been great thus far.” · Mrs Mclean
★★★★★“Luke was very understanding as I am hard of hearing, and I have a home visit arranged with a financial adviser.” · Arwyn
★★★★★“Great way to find an independent adviser. Highly recommended.” · Glenn
★★★★★“Early days but it seems you have matched me with a suitable IFA. Thanks.” · Margaret

Every adviser passes a seven step vetting process. Every one offers whole of market independent advice. And every introduction is free, with no obligation.

Questions people ask

Can I avoid the tax by giving the asset to my children?

No. A gift to anyone other than your spouse or civil partner counts as a sale at market value, so the same gain arises and you have no proceeds to pay it with. Gifts between spouses are the exception, and that is what makes using both partners' positions possible.

I have already exchanged contracts. Is there anything left to do?

For the timing of the gain, no: the exchange date fixes the tax year. Losses, the annual exemption and reliefs still apply, and the plan for the proceeds is entirely open.

Does the 60-day rule apply to my main home?

Only if tax is due. A home that has been your main residence throughout is usually fully covered by private residence relief, with no tax and no report needed. Periods of letting or absence can change that.

Can I use investment losses against a property gain?

Yes. Losses on shares and losses on property are pooled for capital gains purposes. A loss realised on a poorly performing holding this year reduces the tax on a property sold this year.

Do I need an adviser or an accountant?

Both, doing different things. The accountant works out and reports the gain. The adviser plans whose name the asset is in, when it goes, what losses and wrappers are used, and what the money does next.

What does this advice cost?

Usually a fixed fee for the planning work, with an ongoing charge only if the adviser manages the proceeds afterwards. Fees are agreed in writing before anything starts. IFA Connect's introduction is free to you; advisers pay to be part of our network.

Read next

Find an IFA near you

Our growing network of fully vetted, FCA-regulated advisers spans the UK, ready to help with pensions, tax efficiency, investments and retirement.

Find your local IFA today