Your situation

Inheritance or windfall

A lump sum deserves a plan, not a product pitch.

A woman opening letters at her dining table

What kind of lump sum is it?

Search to compare financial advisers.

Put a plan around your lump sum

Wondering what to do with an inheritance in the UK, or with any sudden lump sum, is more common than it feels from the inside. Money arrives from an estate, a property or business sale, or a settlement, and with it comes pressure to do something quickly, usually from people with something to sell.

The honest answer is that the first move is rarely a product. It is a plan: what this money needs to do for you, over what timescale, and how it fits with everything you already have. That is what an independent, whole-of-market adviser builds, and our introduction to one is free and without obligation.

Is this you?

  • You have received, or are about to receive, an inheritance of £100,000 or more.
  • You have sold a property or a business and the money is sitting in a current account.
  • A settlement, redundancy payment or bonus has changed your position in one go.
  • People have started contacting you about managing it, and you want an independent view before you talk to any of them.

How an independent adviser helps with a lump sum

First, the foundations

Before anything is invested: expensive debt, an emergency reserve, and any near-term spending set aside in cash. A good adviser walks through this unglamorous list first, because it is what makes the investing that follows safe.

A goal for every pound

Money for the next two years belongs in different places from money for the next twenty. Splitting the lump sum by purpose, spending, security, growth, gifts, is what turns a balance into a plan.

Investing with the tax wrappers working

ISAs, pensions and general accounts are taxed differently, and using allowances across tax years often adds more than clever fund selection. An adviser sequences contributions so the same portfolio keeps more of its growth.

Keeping an eye on inheritance tax

An inheritance can move your own estate into inheritance tax territory. If that is you, gifting and estate planning belong in the same conversation, done calmly and early rather than urgently and late.
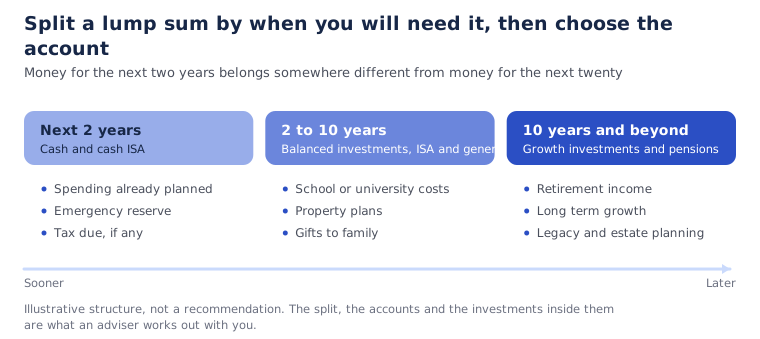
Split a lump sum by when you will need it
Split a lump sum by when you will need it, then choose the account. Money for the next two years, money for the next decade and money for retirement and beyond each belong somewhere different.

What a first pass looks like

Illustrative only. The split and the accounts would be different for every family.

A couple in their fifties inherit £400,000. Both work, one is a higher rate taxpayer, they have a £60,000 mortgage balance and no other debt.

The first conversation with an adviser is not about funds. It covers whether clearing the mortgage beats investing the same money, what a comfortable cash reserve looks like for them, and what the money is actually for over the next twenty years.

Then the tax shelters, in order. Two ISA allowances this tax year, £40,000, and two more after 5 April, another £40,000: £80,000 sheltered within seven months. Pension contributions for the higher rate taxpayer, where £40,000 gross costs around £24,000 after basic and higher rate relief, subject to earnings and the £60,000 annual allowance. The remainder into a general investment account, managed with an eye on the £3,000 capital gains exemption and the £500 dividend allowance each year, and moved into ISAs as allowances renew.

And one thing most people miss: the couple's own estate has just grown by £400,000. If it is now over the allowances, the gifting conversation starts here rather than in twenty years.

Key facts for 2026/27

Last reviewed 30 October 2026

What happens when you get in touch

You tell us roughly how much it is, where it came from, when it arrives and what you think it is for. One of our team calls you within a working day. We then introduce you to an adviser who works with lump sums at your level, usually within a week, and the first meeting is free and without obligation. If the amount or the situation means a simpler route would serve you better, we will say so.

Find your adviser
★★★★★“Professional but informal: after a ten minute chat I was set up with a financial adviser. Really easy and friendly.” · Graham
★★★★★“They took time to assess my specific needs and match me up with a financial adviser with appropriate expertise.” · David
★★★★★“A personal, tailored service like this is invaluable and very reassuring.” · Louise
★★★★★“Asked the right questions, no pushing particular products, and put me in touch with an independent FCA adviser in my area.” · Lucie
★★★★★“I was quickly assigned to an IFA who helped me more with my pension than I’ve received elsewhere.” · Natalie
★★★★★“Kya took the worry out of finding the right company to work with, and it was all done within 24 hours.” · Ruth
★★★★★“Communication with IFA Connect was first class at all stages, and the local IFA is of high calibre.” · Firghil
★★★★★“Luke put me in touch with a financial adviser who met my needs. Excellent, quick and friendly service.” · Adrian
★★★★★“A great experience. I got connected with the adviser very quickly, thanks!” · Paulina
★★★★★“Luke responded within the day and proposed an IFA. The introductory call went well and we are exploring further.” · Mr Makin
★★★★★“I was put in touch with a local financial adviser and his help has been great thus far.” · Mrs Mclean
★★★★★“Luke was very understanding as I am hard of hearing, and I have a home visit arranged with a financial adviser.” · Arwyn
★★★★★“Great way to find an independent adviser. Highly recommended.” · Glenn
★★★★★“Early days but it seems you have matched me with a suitable IFA. Thanks.” · Margaret

Every adviser passes a seven step vetting process. Every one offers whole of market independent advice. And every introduction is free, with no obligation.

Questions people ask

Do I pay tax on an inheritance?

Not on receiving it. Inheritance tax, if any, is settled by the estate before distribution. What you do pay is tax on the interest, dividends and gains the money produces afterwards, which is why where it sits matters.

Should I pay off the mortgage first?

Clearing a mortgage is a guaranteed, tax-free return equal to the interest rate, and for many people the peace of mind is worth more than the arithmetic. Against that, money used to repay debt is no longer available and the same sum invested for twenty years may do more. An adviser puts both routes side by side with your actual rate and timescale.

How quickly do I need to decide?

Slowly. A few months in a savings account with FSCS cover costs very little. The expensive mistakes with lump sums are almost always made fast, and often in response to someone else's deadline.

I have been approached by a wealth manager. What should I ask them?

Whether they are independent or restricted, what the all-in annual cost is including platform and funds, and what happens if you want to leave. Then compare the answers with an independent adviser's. A comparison conversation costs nothing.

Can I just put it all in an ISA?

Not at once. The allowance is £20,000 per person per tax year, so a couple can shelter £40,000 now and £40,000 each April. That is why phasing over several tax years is part of the plan rather than an afterthought.

Does the inheritance change my own inheritance tax position?

Often yes. If your estate is now over £325,000 (or £500,000 including the residence allowance, and double those for a couple), the money you have just received will be taxed again when it passes on unless you plan for it.

What does advice on a lump sum cost?

A fixed fee for the plan, or a percentage of the amount invested, agreed in writing before anything starts. The FCA-cited averages are 2.4% initial and 0.8% a year ongoing. IFA Connect's introduction is free to you; advisers pay to be part of our network.

Read next

Find an IFA near you

Our growing network of fully vetted, FCA-regulated advisers spans the UK, ready to help with pensions, tax efficiency, investments and retirement.

Find your local IFA today