Your situation

Retiring with a £500k+ pension: independent advice

A pension this size opens real choices. The right drawdown plan is what makes them last.

A retired couple laughing together on a bench by the sea with takeaway coffees

How close are you to retiring?

A real person reviews your answers and calls you. Free, no obligation.

We call you back within one working hour, 9am to 6pm, Monday to Friday. Prefer to talk? Call 020 4652 2263

Start your retirement plan

Retiring with a £500k pension, or more, puts you in a strong position and a complicated one. Drawdown or annuity, when to take the tax-free lump sum, which accounts to spend first, how much you can safely draw each year: each answer changes the others, and the tax system does not make the order obvious.

This is the decision set independent advisers deal with every week. Because the advisers we introduce are whole of market and work for you rather than a provider, the plan is built around your retirement, not around keeping your money on any particular platform. Introductions are free and without obligation.

Is this you?

  • You are within five years of stopping work, with pension savings of £500,000 or more between you and your partner.
  • You are weighing drawdown against an annuity and getting different answers from everyone you ask.
  • You are not sure when to take the 25% tax-free lump sum, or whether to take it at all.
  • You are already drawing an income and want to know whether the rate you are taking will last.

How an independent adviser helps at retirement

A drawdown strategy, not just a product

The real question is rarely drawdown versus annuity; it is how much secure income you need, how much flexibility you want, and how the pot supports both. Many good plans blend the two over time.

Taking income tax-efficiently

With pensions, ISAs and other savings in play, the order you draw from them changes the tax you pay across retirement. An adviser sequences withdrawals so more of the same pot ends up as income in your hands.

Making it last

Sustainable withdrawal rates, investment risk that matches the drawdown plan, and regular reviews as markets and spending change: this is the ongoing discipline that separates a plan from a hope.

Thinking past your own retirement

Pensions, inheritance and gifting interact, especially with pension funds due to enter the inheritance tax net from 2027. An adviser helps you decide which assets to spend and which to preserve for family.
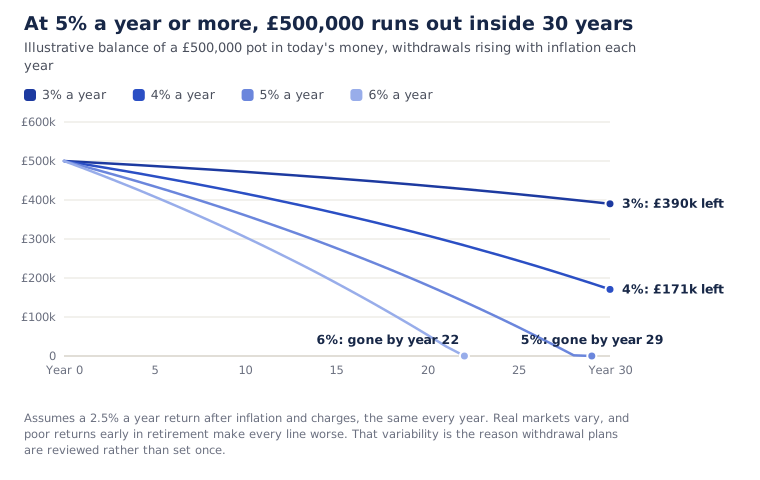
At 5% a year or more, £500,000 runs out inside 30 years
Illustrative balance of a £500,000 pot in today's money at four withdrawal rates, each rising with inflation, assuming a steady 2.5% a year return after inflation and charges. At 3% or 4% the pot lasts thirty years with money to spare. At 5% it is gone in year 29; at 6%, year 22. Real markets are not steady, and poor returns early on make every line worse, which is why withdrawal plans are reviewed rather than set once.

Same income, less tax

Illustrative only. Tax figures use 2026/27 rates and allowances and assume no other income.

Someone retires at 62 with a £600,000 pension and £150,000 in ISAs. State pension starts at 67. She wants £40,000 a year.

Drawing the whole £40,000 as taxable income from the pension costs about £5,486 in income tax each year: the first £12,570 is covered by the personal allowance, and the remaining £27,430 is taxed at 20%.

Drawing £25,000 from the pension and £15,000 from the ISAs gives the same £40,000 in her hands and costs about £2,486 in tax, because only £12,430 of pension income is taxable. That is £3,000 a year less tax for five years, and the tax-free lump sum is still untouched and still growing inside the pension.

From 67 the state pension adds around £12,500 a year and uses up most of the personal allowance, so the sequence changes again. An adviser would also be looking at whether to take the 25% in stages rather than at once, whether a slice of guaranteed income from an annuity makes the rest easier to invest, and, with pensions entering the estate from April 2027, which pot to spend and which to leave.

Key facts for 2026/27

Last reviewed 30 October 2026

What happens when you get in touch

You tell us roughly what you have (pensions, ISAs, property, any final salary pension), when you want to stop and what income you are aiming for. One of our team calls you within one working hour (9am to 6pm, Monday to Friday). We then introduce you to an adviser who specialises in retirement income at your pot size, usually within a week, and the first meeting is free and without obligation.

Find your adviser
★★★★★“Professional but informal: after a ten minute chat I was set up with a financial adviser. Really easy and friendly.” · Graham
★★★★★“They took time to assess my specific needs and match me up with a financial adviser with appropriate expertise.” · David
★★★★★“A personal, tailored service like this is invaluable and very reassuring.” · Louise
★★★★★“Asked the right questions, no pushing particular products, and put me in touch with an independent FCA adviser in my area.” · Lucie
★★★★★“I was quickly assigned to an IFA who helped me more with my pension than I’ve received elsewhere.” · Natalie
★★★★★“Kya took the worry out of finding the right company to work with, and it was all done within 24 hours.” · Ruth
★★★★★“Communication with IFA Connect was first class at all stages, and the local IFA is of high calibre.” · Firghil
★★★★★“Luke put me in touch with a financial adviser who met my needs. Excellent, quick and friendly service.” · Adrian
★★★★★“A great experience. I got connected with the adviser very quickly, thanks!” · Paulina
★★★★★“Luke responded within the day and proposed an IFA. The introductory call went well and we are exploring further.” · Mr Makin
★★★★★“I was put in touch with a local financial adviser and his help has been great thus far.” · Mrs Mclean
★★★★★“Luke was very understanding as I am hard of hearing, and I have a home visit arranged with a financial adviser.” · Arwyn
★★★★★“Great way to find an independent adviser. Highly recommended.” · Glenn
★★★★★“Early days but it seems you have matched me with a suitable IFA. Thanks.” · Margaret

Every adviser passes a seven step vetting process. Every one offers whole of market independent advice. And every introduction is free, with no obligation.

Questions people ask

Drawdown or annuity?

Often both, at different times. The starting question is how much of your income needs to be guaranteed whatever markets do, and how much can flex. Annuity rates have been above 7% for healthy 65 year olds since 2022, which has changed that calculation compared with a decade ago.

Should I take my 25% tax-free lump sum straight away?

It depends on what it is for. Taken and spent on something you had planned, it does its job. Taken and left in a savings account, it has swapped a tax-free environment for a taxable one. Taken in stages as you need it, it can keep growing untaxed in the meantime. An adviser looks at the timing against your other income and the lump sum allowance.

How much can I safely take each year?

There is no single number. The chart above shows why: the gap between 4% and 5% a year is the difference between money left at 30 years and running out before then, even before markets do anything unexpected. A sustainable plan sets a starting rate and then reviews it every year against what has actually happened.

I also have a final salary pension. Does that change things?

Yes, a lot. Guaranteed income from a defined benefit scheme changes how much risk the rest of your money can carry and how much flexibility you need from it. Transferring out of a defined benefit scheme is a separate, heavily regulated decision that needs specialist advice where the value is over £30,000.

How does the April 2027 inheritance tax change affect my retirement?

Until now, leaving the pension until last was the standard approach because it sat outside the estate. From April 2027 that advantage largely goes, and for many people the order of spending changes: pension income earlier, other assets preserved. It is a decision to model, not to assume.

Can I keep paying in after I retire?

Yes, but once you have taken taxable income flexibly from a pension the annual limit for new contributions drops to £10,000. Taking only the tax-free lump sum does not trigger that limit.

What does retirement advice cost?

A fixed fee for the initial plan and an ongoing percentage of what the adviser manages are both common. The FCA-cited average ongoing adviser charge is 0.8% a year. Fees are agreed in writing before any work starts. IFA Connect's introduction is free to you; advisers pay to be part of our network.

Read next

Find an IFA near you

Our growing network of fully vetted, FCA-regulated advisers spans the UK, ready to help with pensions, tax efficiency, investments and retirement.

Find your local IFA today

We call you back within one working hour (9am to 6pm, Monday to Friday).