Your situation

Unhappy with your wealth manager

High fees and generic portfolios are not the only option. See what genuinely independent advice looks like.

A man in glasses reviewing performance charts with a pen

What kind of adviser do you have in place?

Search to compare wealth managers.

Looking for a second opinion?

Thinking about switching wealth manager usually starts quietly: fees that feel high for the service received, a portfolio that looks like everyone else’s, calls that only come at review time. None of it is scandalous, which is exactly why people put up with it for years.

You do not have to decide anything to look at the alternative. The advisers we introduce are genuinely independent and whole of market: they can recommend anything on the market rather than a house range, and their fees are agreed transparently up front. A comparison conversation is free, and switching is only ever your call.

Is this you?

  • You are paying 1.5% a year or more all-in and are not sure what you get for it.
  • Your portfolio is made up entirely of your manager's own funds or model.
  • Your annual review is a call and a report you do not read.
  • Your adviser has left, or the firm has been sold, and you have been passed to someone new.
  • You are not unhappy exactly. You just want to know whether what you have is competitive.

What genuinely independent advice changes

Whole of market, not a house view

A restricted or vertically integrated firm largely recommends its own products and platforms. An independent adviser chooses from the whole market, which changes both the portfolio you get and the fees attached to it.

A fee conversation you can follow

Layered charges, management, platform, funds, transactions, are where wealth management costs hide. An independent adviser sets out the all-in cost of their proposal next to what you pay today, in plain numbers.

A fair second opinion

Sometimes the honest conclusion is that your current arrangement is reasonable. A vetted independent adviser has no house range to defend, so a stay-put recommendation is a real possible outcome, and hearing it costs you nothing.

A managed, unhurried switch

If you do move, the new adviser handles the transfer: what can move as it is, what needs selling, what exit costs apply, and the timing that avoids unnecessary tax. You are never left managing the mechanics yourself.
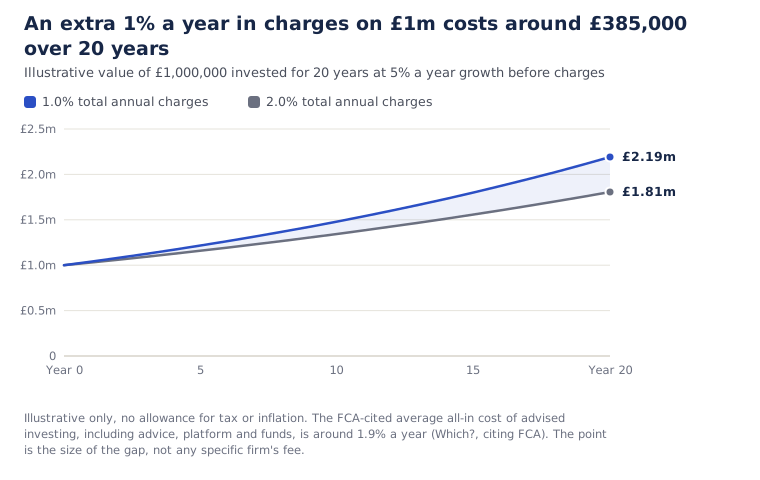
An extra 1% a year in charges on £1m costs around £385,000 over 20 years
£1m invested for twenty years at 5% a year before charges. At 1% total annual charges it grows to around £2.19m; at 2% it reaches around £1.81m. The difference, roughly £385,000, is the cost of one percentage point. Illustrative, with no allowance for tax or inflation.

What a comparison looks like

Illustrative only. The figures are typical of the ranges we see, not any particular firm's charges.

A client has £1.2m with a restricted wealth manager. The adviser charge is 0.75%, the platform 0.35% and the in-house funds average 0.9%. All in, 2.0% a year: £24,000.

An independent adviser's proposal comes back at 0.6% for advice, 0.2% for the platform and 0.35% for the funds. All in, 1.15%: £13,800. The difference is £10,200 a year before any growth on the money saved.

Whether moving is worth it is a separate question, and a fair comparison answers it properly. Are there exit charges on the current products? Can the holdings transfer as they are, or would selling them trigger capital gains tax above the £3,000 exemption? Is the service actually different, or just cheaper? Sometimes the answer that comes back is that the current arrangement is fine. That answer is free too.

Key facts

Last reviewed 30 October 2026

What happens when you get in touch

You tell us roughly what you have invested, who it is with, what you pay if you know, and what has prompted the question. One of our team calls you within a working day. We then introduce you to an independent adviser who does this comparison regularly, usually within a week. They review what you have, cost it against their own proposal, and tell you plainly whether moving is worth it. If it is not, that is the answer, and it costs you nothing.

Find your adviser
★★★★★“Professional but informal: after a ten minute chat I was set up with a financial adviser. Really easy and friendly.” · Graham
★★★★★“They took time to assess my specific needs and match me up with a financial adviser with appropriate expertise.” · David
★★★★★“A personal, tailored service like this is invaluable and very reassuring.” · Louise
★★★★★“Asked the right questions, no pushing particular products, and put me in touch with an independent FCA adviser in my area.” · Lucie
★★★★★“I was quickly assigned to an IFA who helped me more with my pension than I’ve received elsewhere.” · Natalie
★★★★★“Kya took the worry out of finding the right company to work with, and it was all done within 24 hours.” · Ruth
★★★★★“Communication with IFA Connect was first class at all stages, and the local IFA is of high calibre.” · Firghil
★★★★★“Luke put me in touch with a financial adviser who met my needs. Excellent, quick and friendly service.” · Adrian
★★★★★“A great experience. I got connected with the adviser very quickly, thanks!” · Paulina
★★★★★“Luke responded within the day and proposed an IFA. The introductory call went well and we are exploring further.” · Mr Makin
★★★★★“I was put in touch with a local financial adviser and his help has been great thus far.” · Mrs Mclean
★★★★★“Luke was very understanding as I am hard of hearing, and I have a home visit arranged with a financial adviser.” · Arwyn
★★★★★“Great way to find an independent adviser. Highly recommended.” · Glenn
★★★★★“Early days but it seems you have matched me with a suitable IFA. Thanks.” · Margaret

Every adviser passes a seven step vetting process. Every one offers whole of market independent advice. And every introduction is free, with no obligation.

Questions people ask

Would I have to sell everything and start again?

Usually not. Most funds and shares can move between providers as they are. ISAs and pensions transfer as wrappers, so their tax status is untouched. What cannot move is sold, and the tax on that is part of the comparison, not a surprise afterwards.

What if the honest answer is to stay put?

Then you stay put, better informed. An independent adviser has no house range to sell, so "your current arrangement is reasonable" is a normal outcome of a comparison, not a failure.

How do I find out what I am paying now?

Ask your current firm for the annual costs and charges statement in pounds. They are required to provide it. If the number is hard to get, that is itself useful information.

Is a bigger firm safer?

No. Every FCA-authorised firm carries the same Financial Ombudsman and FSCS protection. What size buys is brand, not a guarantee.

Is restricted advice bad?

No. Some restricted firms serve their clients very well. The issue is knowing which you have, because it changes what you are being offered and how it is priced. Many people only discover their adviser is restricted when they ask.

What does a comparison cost?

Nothing. The first meeting with the adviser we introduce is free. If you go ahead, their fees are agreed in writing before any work starts. IFA Connect's introduction is free to you; advisers pay to be part of our network.

Read next

Find an IFA near you

Our growing network of fully vetted, FCA-regulated advisers spans the UK, ready to help with pensions, tax efficiency, investments and retirement.

Find your local IFA today