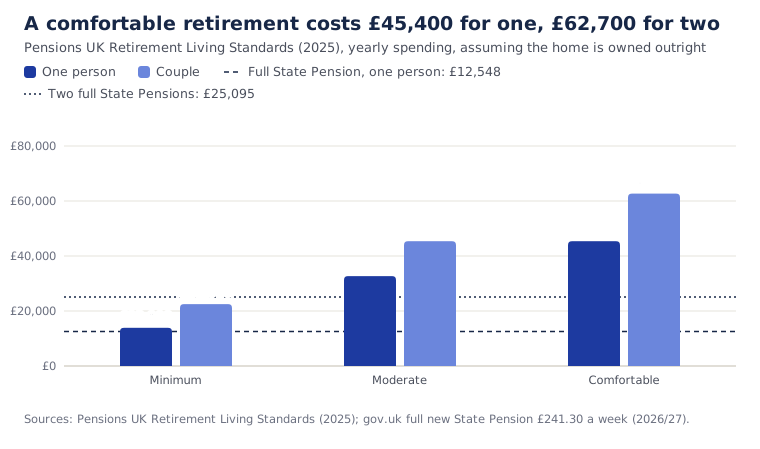
How much you need to retire in the UK depends on the life you want, not on a magic number. Pensions UK's latest standards say one person needs £13,900 a year for a minimum lifestyle, £32,700 for moderate and £45,400 for comfortable.
The State Pension covers part of that. What is left is the gap your pensions and savings must fill, and that sets the size of the pot you need.
Quick answer: Pensions UK puts a moderate retirement at £32,700 a year for one person and a comfortable one at £45,400 (£45,400 and £62,700 for a couple). After a full State Pension of £12,547.60 each, a comfortable retirement needs a pension pot of about £821,000 for one person or £940,000 for a couple, at a 4% yearly withdrawal and before tax.
Key takeaways
- Start with spending, not a pot size. Pensions UK's 2025 standards: £13,900, £32,700 or £45,400 a year for one person.
- The State Pension does a lot of the work. The full rate is £241.30 a week (£12,547.60 a year) in 2026/27. Two full State Pensions cover the minimum standard for a couple.
- A comfortable retirement needs about £821,000 for one person or £940,000 for a couple on top of the State Pension, at a 4% withdrawal rate.
- The withdrawal rate changes everything. At 3.5% the comfortable pot for one person is £938,600; at 5% it is £657,000.
- Retiring early costs more. Bridging seven years from 60 to a State Pension age of 67 at the moderate standard is £228,900 for one person.
Retirement living standards: how much does retirement cost each year?
The most widely used benchmark is the Retirement Living Standards from Pensions UK (formerly the PLSA). They price three lifestyles from real household budgets and assume you own your home outright. The figures are spending, not gross income, so tax comes on top.
| Lifestyle | One person | Gap after full State Pension | Couple | Gap after two full State Pensions |
|---|---|---|---|---|
| Minimum | £13,900 | £1,352 | £22,500 | £0 (covered) |
| Moderate | £32,700 | £20,152 | £45,400 | £20,305 |
| Comfortable | £45,400 | £32,852 | £62,700 | £37,605 |
Sources: Pensions UK Retirement Living Standards (2025); gov.uk full new State Pension £241.30 a week (£12,547.60 a year), 2026/27. As at 15 October 2026.
Minimum covers the basics with some left for social life. Moderate adds a holiday abroad and running a car. Comfortable adds more travel, regular home updates and help for family.
How much pension do I need to retire?
Divide the yearly gap by the share of your pot you plan to withdraw each year. At a 4% withdrawal rate, every £1,000 of yearly income above the State Pension needs about £25,000 in your pension.
| Lifestyle | Pot at 5% withdrawal | Pot at 4% withdrawal | Pot at 3.5% withdrawal |
|---|---|---|---|
| Moderate, one person | £403,000 | £503,800 | £575,800 |
| Moderate, couple | £406,100 | £507,600 | £580,100 |
| Comfortable, one person | £657,000 | £821,300 | £938,600 |
| Comfortable, couple | £752,100 | £940,100 | £1,074,400 |
IFA Connect calculation: (spending − full State Pension) ÷ withdrawal rate, rounded to the nearest £100. Before tax and charges. Minimum standard: one person needs about £33,800 at 4%; a couple needs no pot if both get the full State Pension.
How much do I need to retire comfortably in the UK?
To retire comfortably in the UK, one person needs about £45,400 a year and a couple £62,700 (Pensions UK). After the State Pension, that means a pension pot of about £821,300 for one person or £940,100 for a couple at a 4% withdrawal rate, before tax.
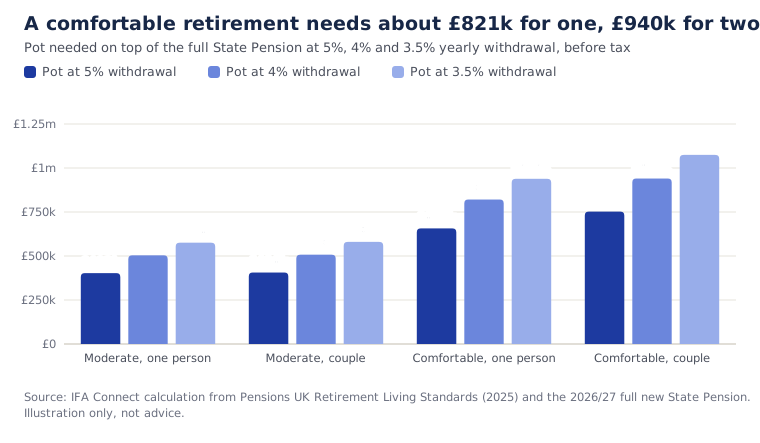
At a more cautious 3.5% withdrawal rate, a comfortable pot rises to £938,600 for one person and £1,074,400 for a couple. At 5% it falls to £657,000 and £752,100.
Before you rely on these numbers
The value of investments can go down as well as up, and you may get back less than you put in.
These figures are before income tax. The full State Pension uses all but £22.40 of the £12,570 personal allowance, so most pension income above your tax-free cash is taxed.
How much does a couple need to retire? A worked example
A couple needs £22,500 a year for a minimum retirement, £45,400 for moderate and £62,700 for comfortable (Pensions UK). Two full State Pensions cover the minimum, so the pot only has to fund the rest. Here is the full sum for a moderate retirement.
Priya and David are both 60, own their home and want the moderate standard. Both expect the full State Pension at 67.
| Step | Calculation | Result |
|---|---|---|
| 1. Spending target | Pensions UK moderate, couple | £45,400 |
| 2. State Pension | 2 × £241.30 × 52 | £25,095.20 |
| 3. Gap to fill each year | £45,400 − £25,095.20 | £20,304.80 |
| 4. Pot at 4% withdrawal | £20,304.80 ÷ 0.04 | £507,600 |
| 5. Bridge to State Pension age | 7 years × £45,400 (60 to 67) | £317,800 |
| Total to have in place at 60 | Step 4 + Step 5, before growth and tax | £825,400 |
IFA Connect calculation. Illustrative only: ignores investment growth, inflation, tax and charges during the bridging years.
Retiring at 60 adds over 60% to what they need, about £318,000 more than waiting for the State Pension. That is the single biggest lever most people have.
Notice that a couple needs barely more than one person for a moderate retirement: £507,600 against £503,800. Two State Pensions cover far more of the couple's £45,400 than one does of £32,700.
How long will my pension last? The £500,000 example
How long your pension lasts depends mostly on how much you take out. With 4% yearly growth after charges and withdrawals rising 2.5% a year for inflation, taken at the end of each year, a £500,000 pot runs out in year 33 at £20,000 a year, but in year 20 at £30,000.
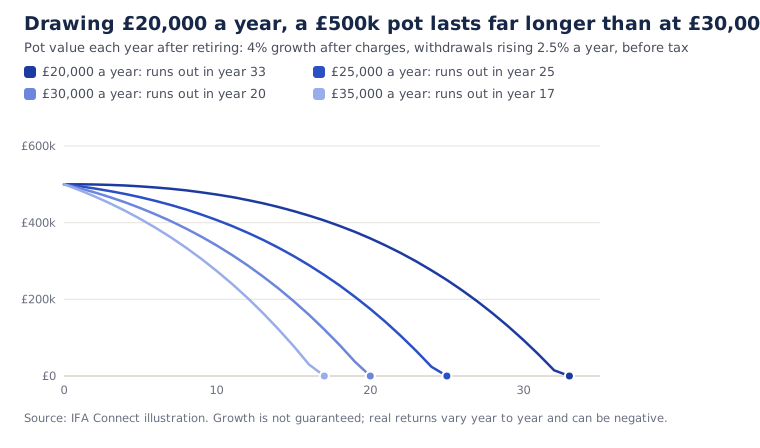
Real returns vary year to year, and a fall in the first few years of withdrawals does the most damage. Our page on retiring with £500k explains how an adviser can help you plan around that.
How much do I need to retire at 55 or 60?
To retire at 55 or 60, you need enough to cover every year before your State Pension starts, on top of the pot for later life. You can usually take a personal pension from 55, rising to 57 from 6 April 2028; the State Pension starts at 66, rising to 67 between 2026 and 2028.
| Retire at | Years to fund before 67 | Moderate, one person | Comfortable, one person | Comfortable, couple |
|---|---|---|---|---|
| Retire at 55 | 12 years | £392,400 | £544,800 | £752,400 |
| Retire at 57 | 10 years | £327,000 | £454,000 | £627,000 |
| Retire at 60 | 7 years | £228,900 | £317,800 | £438,900 |
| Retire at 63 | 4 years | £130,800 | £181,600 | £250,800 |
IFA Connect calculation: Pensions UK yearly spending × years. Before growth, inflation and tax. Normal minimum pension age: Finance Act 2022.
The key rules that set your number
| Rule | 2026/27 figure | Why it matters | Source |
|---|---|---|---|
| Full new State Pension | £241.30 a week (£12,547.60 a year) | Reduces the pot you need | gov.uk |
| Qualifying years | 35 for the full rate; usually 10 minimum | Gaps reduce your State Pension | gov.uk |
| State Pension age | 66, rising to 67 between 2026 and 2028 | Sets the bridging years | gov.uk |
| Earliest pension access | 55, rising to 57 from 6 April 2028 | Limits early retirement | Finance Act 2022 |
| Tax-free cash | Usually 25%, up to £268,275 in total | Boosts net income | gov.uk |
| Personal allowance | £12,570 | Most is used by the State Pension | gov.uk |
As at 15 October 2026.
How to work out your own retirement number in five steps
The quickest way to answer “how much do I need to retire?” for your own life is this five-step sum. It takes about ten minutes with your State Pension forecast to hand.
- Write down what you spend now and what will change when you stop work (commuting, mortgage, travel).
- Pick the Pensions UK standard closest to that, or use your own figure.
- Get your State Pension forecast on gov.uk and subtract it from your spending.
- Divide the gap by 0.04 for a starting pot size, and add the years you need to bridge before State Pension age.
- Add up every pension, ISA and saving you have. Our guide to combining old pensions helps if yours are scattered.
If your total falls short, the main levers are retiring later, spending less or paying more in now. An adviser can model those trade-offs with tax and investment growth included.
When should you speak to an independent financial adviser?
A rule of thumb tells you roughly how much you need to retire. Advice is worth it when the decisions get expensive to get wrong:
- You have £250,000 or more across pensions and savings and want to know if it is enough.
- You want to retire before your State Pension age.
- You are deciding between drawdown, an annuity or a mix.
- You have several old workplace pensions. See our pension review page.
- You want to pass money on, as unused pensions count for inheritance tax from April 2027. See pensions and inheritance tax from 2027 and the inheritance tax threshold.
IFA Connect does not give advice. A real person learns what you need and introduces you to one independent, FCA-regulated adviser who can look at the whole market. Why independent matters · How we vet our advisers · Retirement advice.
We typically introduce people with £250,000 or more in investable assets.
Find your local IFA: a real person matches you with one vetted, independent adviser. Our introduction is free; advisers explain their fees before you commit.
Frequently asked questions
How much do I need to retire on £30,000 a year?
One person with a full State Pension of £12,547.60 needs to draw about £17,450 a year from savings to reach £30,000 before tax. At a 4% withdrawal rate that is a pension pot of about £436,300.
How much pension do I need to retire?
Take the yearly spending you want, subtract the State Pension you expect, and divide the gap by a sustainable withdrawal rate. At 4%, every £1,000 a year of income above the State Pension needs about £25,000 in your pension pot.
Is £500,000 enough to retire?
For one person it can be. Drawing 4% gives £20,000 a year, and with a full State Pension that is about £32,500, close to the £32,700 moderate standard. It falls short of the comfortable standard and depends on tax, fees and returns. See retiring with £500k.
Is the State Pension enough for a couple to retire on?
Two full State Pensions give £25,095.20 a year. That covers Pensions UK's £22,500 minimum standard for a couple but not the £45,400 moderate standard, which needs a pension pot of about £507,600 at a 4% withdrawal rate on top.
Does the State Pension count towards what I need?
Yes. The full new State Pension is £241.30 a week in 2026/27, or £12,547.60 a year, if you have 35 qualifying years of National Insurance. Check your forecast on gov.uk, then plan your savings to cover the gap.
Can I retire at 55?
You can usually take a personal pension from 55, rising to 57 from 6 April 2028. The State Pension starts at 66, rising to 67 between 2026 and 2028, so your savings must cover the years in between as well as later life.
What is the 4% rule?
It is a rule of thumb that drawing 4% of your pot in the first year, then rising with inflation, has historically lasted around 30 years. It comes from US market research, is not guaranteed, and ignores tax and charges, so treat it as a starting point.